

Editor's Choice
Blackwattle takes over Quest Asset Partners
Blackwattle Investment Partners has swallowed up Australian equities manager Quest Asset Partners for an undisclosed sum.
Funds SA poaches Vision Super risk specialist
Funds SA will welcome a Vision Super executive to replace executive director, governance and strategy Tony Burrill, as he prepares for retirement following a seven-year tenure at the company.
Regal flags muted second-half performance fees
Regal Partners expects to recognise at least $122.7 million in fund performance fee revenue for calendar 2026, with market volatility and weaker investment performance limiting the prospect of further material fees in the second half.
Insignia chief draws 'hard line' on NCAs giving retirement advice
Insignia Financial chief executive Scott Hartley said he draws a hard line when it come to the new class of advisers (NCAs) giving retirement advice.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
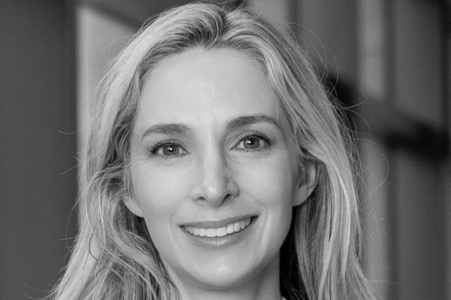
Fiona Macgregor
GROUP CHIEF EXECUTIVE AND MANAGING DIRECTOR
TAL LIMITED
TAL LIMITED
Fiona Macgregor has risen through the ranks at TAL, taking the top job in 2024, but her life was touched by the insurance sector long before her tenure with the life insurer began. Eliza Bavin writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


Keating is spot on, except he does not go far enough. The first element of "overhauling" the current Superannuation system is for compulsory contributions by employees. The billions of dollars held in "lost" Superannuation accounts demonstrates that the majority of people do not really see it as their money as they have put no evident skin in the game. Having the contributions made solely by employers gives this impression. Certainly a case can be put 100% that salaries and wages have been and are "adjusted" to allow for the cost of the contributions which could then lead to an impression that the employee is paying. The important issue is the impression & they do not really see this.
The second element is increasing the employer component. I would leave it to someone with superior knowledge like a Paul Keating to accurately (??) determine what is needed. The third element is that there are hundreds of thousands of self employed (sole traders and/or those operating under a partnership) who are not compelled to contribute for their future.
They should have to pay a prescribed higher rate of tax with the increase going towards Superannuation. Little Johnnie was indeed kind with the halving of the Assets Test, but one must also consider that Politicians on taxpayer funded Superannuation (and others) became substantial beneficiaries of the removal of taxation on pensions or moneys extracted from Superannation after age 60. A fourth element should be increasing the age that one can access Superannuation monies. Those who perform heavy duty manual work need to be considered carefully in whatever changes take place as they generally have shorter working capabilities.