

Editor's Choice
FAAA says super trustees should stump up for CSLR
The Financial Advice Association Australia (FAAA) has called on Treasury to cut the Compensation Scheme of Last Resort (CSLR) special levy on the advice sector to zero and for superannuation trustees to stump up for the scheme.
HESTA unveils new leaders for property, financial risk
HESTA has named a pair of general managers, who will be joining the $107 billion super fund, joining from Aware Super and QIC.
ASIC issues more stop orders amid private credit crackdown
ASIC has issued another stop order on a PDS offering units in three registered managed investment schemes.
Life CCC spots 10.6k breaches in FY26
The Life Code Compliance Committee has published its FY26 annual report, which saw over 10,600 breaches by insurers with close to 30,000 customers affected.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
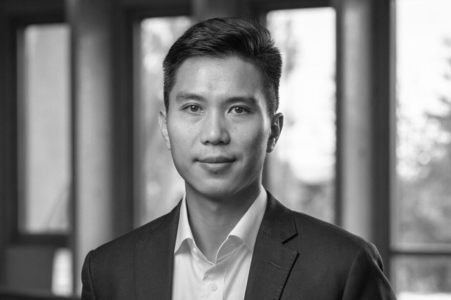
Cliff Man
CHIEF EXECUTIVE OFFICER
ETF SHARES MANAGEMENT LTD
ETF SHARES MANAGEMENT LTD
ETF Shares chief executive Cliff Man spent his career automating, building and challenging established systems. Now, he is betting that Australia's ETF market has room for something different. Vinny Vucago writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


Keating is spot on, except he does not go far enough. The first element of "overhauling" the current Superannuation system is for compulsory contributions by employees. The billions of dollars held in "lost" Superannuation accounts demonstrates that the majority of people do not really see it as their money as they have put no evident skin in the game. Having the contributions made solely by employers gives this impression. Certainly a case can be put 100% that salaries and wages have been and are "adjusted" to allow for the cost of the contributions which could then lead to an impression that the employee is paying. The important issue is the impression & they do not really see this.
The second element is increasing the employer component. I would leave it to someone with superior knowledge like a Paul Keating to accurately (??) determine what is needed. The third element is that there are hundreds of thousands of self employed (sole traders and/or those operating under a partnership) who are not compelled to contribute for their future.
They should have to pay a prescribed higher rate of tax with the increase going towards Superannuation. Little Johnnie was indeed kind with the halving of the Assets Test, but one must also consider that Politicians on taxpayer funded Superannuation (and others) became substantial beneficiaries of the removal of taxation on pensions or moneys extracted from Superannation after age 60. A fourth element should be increasing the age that one can access Superannuation monies. Those who perform heavy duty manual work need to be considered carefully in whatever changes take place as they generally have shorter working capabilities.