

Editor's Choice
SGHiscock acquires Bell Asset Management
SGHiscock will acquire Bell Asset Management, giving the two Melbourne-based active managers greater scale.
JPMAM launches global value strategy
J.P. Morgan Asset Management has launched a new strategy, available via a managed fund and an ETF, for Australian investors seeking active exposure in attractively valued companies across global equity markets.
Episodic advice captures younger generations
Wealthadvice managing director Marisa Broome believes episodic advice is a "great way of capturing the younger generation" since she can help them establish sensible financial decisions at a relatively younger age.
Competing forces challenge traditional group insurance design
Premium increases, default cover volatility and the mental health crisis are forcing super funds and life insurance partners to redesign group insurance.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
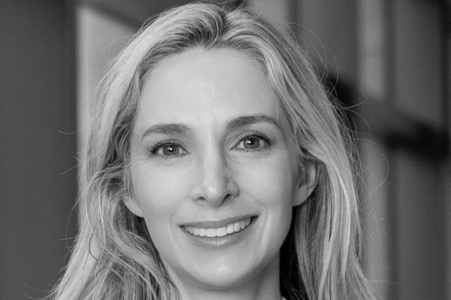
Fiona Macgregor
GROUP CHIEF EXECUTIVE AND MANAGING DIRECTOR
TAL LIMITED
TAL LIMITED
Fiona Macgregor has risen through the ranks at TAL, taking the top job in 2024, but her life was touched by the insurance sector long before her tenure with the life insurer began. Eliza Bavin writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


Of course it's over-regulation; in fact overkill.
Of course, there was room for improvement - not necessarily by regulation - throughout the whole financial services industry; there always was, there always will be, as with any area of human activity.
But for ASIC to bulldoze it's way through the financial adviser profession - probably the softest option of course - as if financial advisers were anti-social, self-serving incompetents, has been, and remains a stain on a body that has shamefully failed miserably to serve the public interest.
It's rather like a government's appointing a committee with virtually carte-blanche powers to examine the efficiency of the Armed Forces, then despite the fact of the troops in the trenches fighting to their utmost ability, decide to shoot the troops. Or at least, make their task virtually impossible.
And, of course, the Chiefs of Staff were afraid to speak up for fear of ASIC's charging them with self-interest, and thereby risking being ostracised.
All with one inevitable result.
Maybe we're going to wake up soon and - even if we allow that they had well-meaning intent - realise that ASIC's actions resulted in a disastrous shortage of financial care and guidance for the vast majority of Australia's everyday 'ordinary folk'.
And furthermore, made such care and guidance too costly and unviable to those financial advisers who remain.
Hi I joined the Industry in 1974 all you needed was a rate book a pen and some applications I left recently due to the red tape required to do the simplest of tasks for a client, a lot of really good people have walked away after giving a lifetime of work that most other can,t do, keep it simple was the rule, now unless you are totally process driven and thrive on prepareing totally usless reports, you're gone. In this enviroment how hard is putting stop losses, most new advisers dont understand them with the red tape they are now impossible to use. they have there place.
I'm probably the only person who is going to thank you wonderful people who gave up your nights to make a living and help others look after them selves. You should have been given a medal for service to the community for selling a product that was so desperately needed in tragic circumstances.
Bruce Carter