
ASIC issues warning over Dover advisersBY JAMIE WILLIAMSON | WEDNESDAY, 13 JUN 2018 12:46PMAdvice licensees considering onboarding ex-Dover Financial Advisers' authorised representatives have been warned to ramp up due diligence processes by the corporate regulator. Related News |


Editor's Choice
FAAA says super trustees should stump up for CSLR
The Financial Advice Association Australia (FAAA) has called on Treasury to cut the Compensation Scheme of Last Resort (CSLR) special levy on the advice sector to zero and for superannuation trustees to stump up for the scheme.
HESTA unveils new leaders for property, financial risk
HESTA has named a pair of general managers, who will be joining the $107 billion super fund, joining from Aware Super and QIC.
ASIC issues more stop orders amid private credit crackdown
ASIC has issued another stop order on a PDS offering units in three registered managed investment schemes.
Life CCC spots 10.6k breaches in FY26
The Life Code Compliance Committee has published its FY26 annual report, which saw over 10,600 breaches by insurers with close to 30,000 customers affected.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
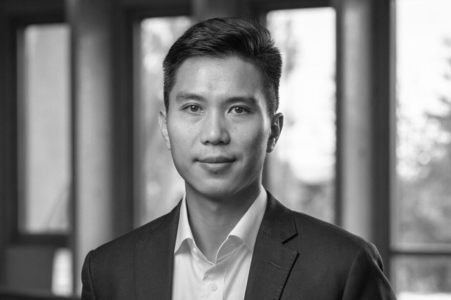
Cliff Man
CHIEF EXECUTIVE OFFICER
ETF SHARES MANAGEMENT LTD
ETF SHARES MANAGEMENT LTD
ETF Shares chief executive Cliff Man spent his career automating, building and challenging established systems. Now, he is betting that Australia's ETF market has room for something different. Vinny Vucago writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


Now being retired, but having spent 50 years looking after the financial security of many hundreds of clients - typical, everyday Australians - I see the present, heavy-handed, neo-vindictive attitude of ASIC (at least, certain 'power wielders' in ASIC) as a real threat to the financial security and well-being of the majority of those everyday Australians whose interests it purports to protect.
ASIC's attitude and practices effectively jeopardise the delivery of much-needed services by firstly demonising those in daily contact with, and who look after the interests of, their clients, and secondly by the imposition of a compliance regime that holds process above the delivery of empathetic, creative and beneficial financial planning services.
This is not to say that ASIC does not have a necessary, indeed noble, purpose. But it's present policy of guilty until proven innocent, does nothing to uphold that noble purpose; in fact, quite the contrary.
The present debacle of ASIC's closure of Dover Financial, and in consequence - but far more importantly - the denial of access to the normal, everyday financial services provided by the 400 Dover advisers, must undoubtably compute to at least 20,000 (that's only an average of 50 clients per adviser, so the number could be far higher) Clients' being denied the assistance they would otherwise be receiving. And - in case not considered relevant by ASIC - it happens to be Financial Year-end!
One can only imagine the many offices of the (now rendered impotent) advisers, with their staff's not being able to assist their thousands of needy clients, and indeed now wondering about their own financial security.
Justified ASIC may be, in closing Dover. But to assume a guilty verdict on all 400 Advisers, thus denying the delivery of everyday services to their tens of thousands of clients, cannot be justified.
Imagine closing all the branches of a bank because someone at head office had done the wrong thing.