
Life insurance faces worst conditions in decadesBY LAURA MILLAN | TUESDAY, 5 NOV 2013 12:20PMWith shareholder returns in free fall, the life insurance industry is facing its worst conditions in decades, an Ernst & Young Australia (EY) analysis of the full year banking results found. Related News |


Editor's Choice
IFM looks offshore for renewable lending opportunities
|Australia is losing out to the global market and increasingly to Asia when it comes to renewables lending from one of the country's biggest fund managers, with IFM Investors executive director and co-head of APAC diversified credit Hiran Wanigasekera saying the risk-return trade-off is simply better ...
GQG records further outflows despite positive returns
|GQG Partners recorded net outflows of $3.3 billion (US$2.3bn) in September, extending a difficult year for the ASX-listed fund manager despite positive investment performance across its four primary strategies.
Mason Stevens farewells managing director
|Mason Stevens managing director, global investment service has wrapped up his seven-year tenure at the company.
ASX to defend legal action brought by shareholder
|The Australian Securities Exchange said it plans to defend the claims submitted by one of its shareholders on ASX's behalf, stating the applications filed are "not in the best interests of the company."

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
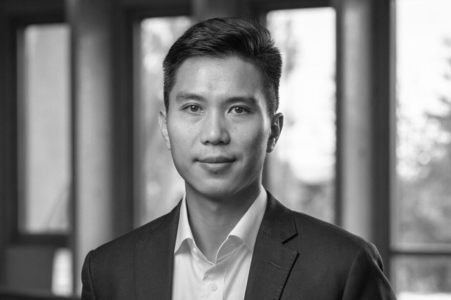
Cliff Man
CHIEF EXECUTIVE OFFICER
ETF SHARES MANAGEMENT LTD
ETF SHARES MANAGEMENT LTD
ETF Shares chief executive Cliff Man spent his career automating, building and challenging established systems. Now, he is betting that Australia's ETF market has room for something different. Vinny Vucago writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


It is not surprising that the Life insurers are staggering under the weight of claims principally coming from the Industry super fund segment. The cost of insurance in this segment with no evidence of health being a promotion tool used against "normal" life insurance channels is not backfiring on the funds and the insurers.
Look to 40% plus rises in premiums, and also look to a decrease in thresholds for full underwriting. As well look to some of these policies carrying exclusions for disability claims for the first 2 years.
The evidence is that some of the majors have been very badly burnt by the Industry super fund deals and will now have to claw back cash or dump the cover and leave the funds to their own devices as costs exceed returns in absolute terms.