

Editor's Choice
Corporate, governance issues fuel whistleblower tipoffs: ASIC
The corporate regulator received nearly 2000 tip offs from whistleblowers in the last financial year, a whopping 183% jump annually, the majority of which relate to corporate and governance issues.
Platinum awards mandate, changes fund name
Platinum Asset Management has awarded a mandate to a US-based investment manager to oversee investment capabilities in a 20-year-old fund, simultaneously altering the name to reflect the update.
Workplace mental ill-health can cost Australia $27bn: Report
Workplace mental health issues are directly costing the Australian economy $12 billion per annum in lost gross domestic product (GDP), with the cost set to rise by more than 125% over the next 15 years in excess of $27 billion a year.
ASX turns up heat on Clime Capital following KPMG scrutiny
The ASX has also raised concerns over Clime Capital's valuation of its unlisted assets portfolio and the qualified opinion that was eventually handed down by its auditor KPMG.
Further Reading
Products
Expert Feed
When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...
Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
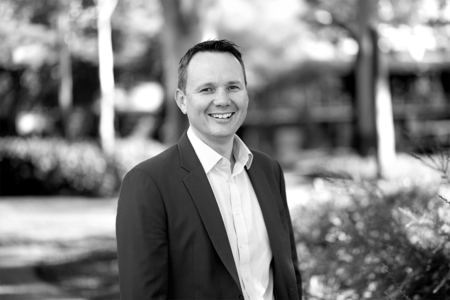
David Sharpe
CHAIRMAN
FINANCIAL ADVICE ASSOCIATION AUSTRALIA
FINANCIAL ADVICE ASSOCIATION AUSTRALIA
A family man, business owner, cricket fanatic and financial adviser, David Sharpe has many facets. One of his biggest legacies, as he steps down as chair of the Financial Advice Association Australia, is leaving the profession stronger than he found it.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |




Of course it's over-regulation; in fact overkill.
Of course, there was room for improvement - not necessarily by regulation - throughout the whole financial services industry; there always was, there always will be, as with any area of human activity.
But for ASIC to bulldoze it's way through the financial adviser profession - probably the softest option of course - as if financial advisers were anti-social, self-serving incompetents, has been, and remains a stain on a body that has shamefully failed miserably to serve the public interest.
It's rather like a government's appointing a committee with virtually carte-blanche powers to examine the efficiency of the Armed Forces, then despite the fact of the troops in the trenches fighting to their utmost ability, decide to shoot the troops. Or at least, make their task virtually impossible.
And, of course, the Chiefs of Staff were afraid to speak up for fear of ASIC's charging them with self-interest, and thereby risking being ostracised.
All with one inevitable result.
Maybe we're going to wake up soon and - even if we allow that they had well-meaning intent - realise that ASIC's actions resulted in a disastrous shortage of financial care and guidance for the vast majority of Australia's everyday 'ordinary folk'.
And furthermore, made such care and guidance too costly and unviable to those financial advisers who remain.
Hi I joined the Industry in 1974 all you needed was a rate book a pen and some applications I left recently due to the red tape required to do the simplest of tasks for a client, a lot of really good people have walked away after giving a lifetime of work that most other can,t do, keep it simple was the rule, now unless you are totally process driven and thrive on prepareing totally usless reports, you're gone. In this enviroment how hard is putting stop losses, most new advisers dont understand them with the red tape they are now impossible to use. they have there place.
I'm probably the only person who is going to thank you wonderful people who gave up your nights to make a living and help others look after them selves. You should have been given a medal for service to the community for selling a product that was so desperately needed in tragic circumstances.
Bruce Carter