

Editor's Choice
IFM Investors appoints global product strategy head
|IFM Investors has strengthened its global leadership team with a senior appointment of a former WTW consultant.
Macquarie AM launches venture growth fund
|The new fund will provide eligible investors access to late-stage growth companies around the world based on a two-decade track record with more than 350 investments.
Consistent climate disclosures matter: ASFA, ACSI
|The Association of Superannuation Funds Australia (ASFA) and the Australian Council of Superannuation Investors (ACSI have joined four other peak investment bodies to push for continued transparent and comparable climate disclosure.
Ironbark expands advice footprint with acquisition
|Ironbark Financial Group has acquired a Victoria-based multi-disciplinary firm that specialises in assisting small to medium sized businesses, integrating the practice into its Ironbark Advice brand.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
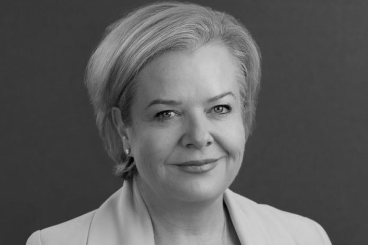
Jacqueline Fernley
CHIEF EXECUTIVE OFFICER
ARC POINT OCIO PTY LTD
ARC POINT OCIO PTY LTD
Jacqueline Fernley is a self-confessed nerd, a market animal and as of this year, her own boss. Riddhima Talwani writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


Of course it's over-regulation; in fact overkill.
Of course, there was room for improvement - not necessarily by regulation - throughout the whole financial services industry; there always was, there always will be, as with any area of human activity.
But for ASIC to bulldoze it's way through the financial adviser profession - probably the softest option of course - as if financial advisers were anti-social, self-serving incompetents, has been, and remains a stain on a body that has shamefully failed miserably to serve the public interest.
It's rather like a government's appointing a committee with virtually carte-blanche powers to examine the efficiency of the Armed Forces, then despite the fact of the troops in the trenches fighting to their utmost ability, decide to shoot the troops. Or at least, make their task virtually impossible.
And, of course, the Chiefs of Staff were afraid to speak up for fear of ASIC's charging them with self-interest, and thereby risking being ostracised.
All with one inevitable result.
Maybe we're going to wake up soon and - even if we allow that they had well-meaning intent - realise that ASIC's actions resulted in a disastrous shortage of financial care and guidance for the vast majority of Australia's everyday 'ordinary folk'.
And furthermore, made such care and guidance too costly and unviable to those financial advisers who remain.
Hi I joined the Industry in 1974 all you needed was a rate book a pen and some applications I left recently due to the red tape required to do the simplest of tasks for a client, a lot of really good people have walked away after giving a lifetime of work that most other can,t do, keep it simple was the rule, now unless you are totally process driven and thrive on prepareing totally usless reports, you're gone. In this enviroment how hard is putting stop losses, most new advisers dont understand them with the red tape they are now impossible to use. they have there place.
I'm probably the only person who is going to thank you wonderful people who gave up your nights to make a living and help others look after them selves. You should have been given a medal for service to the community for selling a product that was so desperately needed in tragic circumstances.
Bruce Carter