

Editor's Choice
FAAA says super trustees should stump up for CSLR
The Financial Advice Association Australia (FAAA) has called on Treasury to cut the Compensation Scheme of Last Resort (CSLR) special levy on the advice sector to zero and for superannuation trustees to stump up for the scheme.
HESTA unveils new leaders for property, financial risk
HESTA has named a pair of general managers, who will be joining the $107 billion super fund, joining from Aware Super and QIC.
ASIC issues more stop orders amid private credit crackdown
ASIC has issued another stop order on a PDS offering units in three registered managed investment schemes.
Life CCC spots 10.6k breaches in FY26
The Life Code Compliance Committee has published its FY26 annual report, which saw over 10,600 breaches by insurers with close to 30,000 customers affected.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
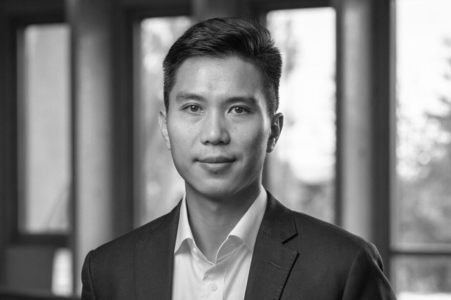
Cliff Man
CHIEF EXECUTIVE OFFICER
ETF SHARES MANAGEMENT LTD
ETF SHARES MANAGEMENT LTD
ETF Shares chief executive Cliff Man spent his career automating, building and challenging established systems. Now, he is betting that Australia's ETF market has room for something different. Vinny Vucago writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


Of course it's over-regulation; in fact overkill.
Of course, there was room for improvement - not necessarily by regulation - throughout the whole financial services industry; there always was, there always will be, as with any area of human activity.
But for ASIC to bulldoze it's way through the financial adviser profession - probably the softest option of course - as if financial advisers were anti-social, self-serving incompetents, has been, and remains a stain on a body that has shamefully failed miserably to serve the public interest.
It's rather like a government's appointing a committee with virtually carte-blanche powers to examine the efficiency of the Armed Forces, then despite the fact of the troops in the trenches fighting to their utmost ability, decide to shoot the troops. Or at least, make their task virtually impossible.
And, of course, the Chiefs of Staff were afraid to speak up for fear of ASIC's charging them with self-interest, and thereby risking being ostracised.
All with one inevitable result.
Maybe we're going to wake up soon and - even if we allow that they had well-meaning intent - realise that ASIC's actions resulted in a disastrous shortage of financial care and guidance for the vast majority of Australia's everyday 'ordinary folk'.
And furthermore, made such care and guidance too costly and unviable to those financial advisers who remain.
Hi I joined the Industry in 1974 all you needed was a rate book a pen and some applications I left recently due to the red tape required to do the simplest of tasks for a client, a lot of really good people have walked away after giving a lifetime of work that most other can,t do, keep it simple was the rule, now unless you are totally process driven and thrive on prepareing totally usless reports, you're gone. In this enviroment how hard is putting stop losses, most new advisers dont understand them with the red tape they are now impossible to use. they have there place.
I'm probably the only person who is going to thank you wonderful people who gave up your nights to make a living and help others look after them selves. You should have been given a medal for service to the community for selling a product that was so desperately needed in tragic circumstances.
Bruce Carter