
Advisers report burnout, breaking point: ResearchBY KARREN VERGARA | TUESDAY, 25 MAY 2021 12:18PM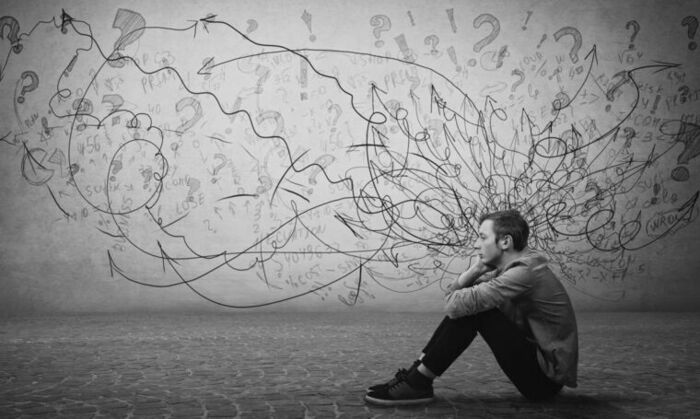 High levels of stress and anxiety are tempting 42% of financial advisers to exit the industry, as reports of burnout underscore the toll their work is taking on their physical and mental health, new research suggests. |


Editor's Choice
SGHiscock acquires Bell Asset Management
SGHiscock will acquire Bell Asset Management, giving the two Melbourne-based active managers greater scale.
JPMAM launches global value strategy
J.P. Morgan Asset Management has launched a new strategy, available via a managed fund and an ETF, for Australian investors seeking active exposure in attractively valued companies across global equity markets.
Episodic advice captures younger generations
Wealthadvice managing director Marisa Broome believes episodic advice is a "great way of capturing the younger generation" since she can help them establish sensible financial decisions at a relatively younger age.
Competing forces challenge traditional group insurance design
Premium increases, default cover volatility and the mental health crisis are forcing super funds and life insurance partners to redesign group insurance.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
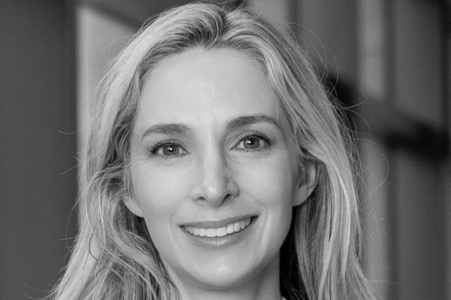
Fiona Macgregor
GROUP CHIEF EXECUTIVE AND MANAGING DIRECTOR
TAL LIMITED
TAL LIMITED
Fiona Macgregor has risen through the ranks at TAL, taking the top job in 2024, but her life was touched by the insurance sector long before her tenure with the life insurer began. Eliza Bavin writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


The Government and people involved should feel ashamed for instigating this circumstance for a group of working people
The real cause for concern is the vast body of advisers who have not sought medical help, but nevertheless slog on under the unprecedented onslaught of savage bureaucratic imposts that have undermined the viability of the majority of financial advisers' businesses.
The quantity and frequency of ASIC-invented compliance requirements - for example, having to duplicate and often triplicate adviser fee reporting on a repeated basis, plus the sheer quantity of mindless, usually confusing communications imposed on Clients - has clearly and deliberately been designed by ASIC to undermine the efficiency and viability of the profession.
The affected advisers who remain in practice do so out of loyalty and fidelity to their Clients, and despite their savagely reduced earnings and crippling ASIC-imposed increased costs.
Has ever a profession been so victimized?
We have to ask Why?
Sadly everyone is either too busy doing compliance paperwork or too depressed to comment.