

Editor's Choice
AIA snags Acenda head of products
AIA Australia has welcomed a new head of partnerships, who joined from Acenda after leaving the firm in March.
Praemium chief exits amid leadership renewal
Praemium is reshuffling its top leadership to refresh its strategy, keeping the same goals but with "faster pace, better execution and increased focus on customers".
ASIC lifts stop orders against Remara
ASIC has lifted three interim stop orders against Remara Investment Management's private credit products, after it amended its target market determination (TMD).
Brookfield-owned Oaktree raises US$2bn for private credit fund
Brookfield-owned Oaktree has achieved its target fund raise of US$2 billion for its Asset-Backed Financial Fund.

Further Reading
Products
Expert Feed

When geopolitics becomes a portfolio risk
Geopolitics is back - again - and Australian investors can no longer treat it as distant background noise.
Does association membership still matter?
With all the changes the advice sector has experienced in recent years, such as regulatory reform and increased education and professional standards ...

Digital assets and where they stand in 2026
So far in 2026 digital assets have captured the headlines largely for the wrong reasons, but that doesn't tell the full story.
Rethinking default design in a changing market environment
The evolution underway in the US DC system highlights the value of periodically reassessing default design assumptions.
Featured Profile
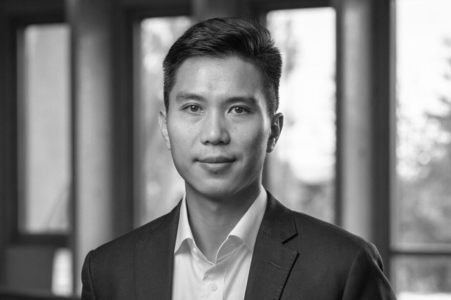
Cliff Man
CHIEF EXECUTIVE OFFICER
ETF SHARES MANAGEMENT LTD
ETF SHARES MANAGEMENT LTD
ETF Shares chief executive Cliff Man spent his career automating, building and challenging established systems. Now, he is betting that Australia's ETF market has room for something different. Vinny Vucago writes.
The Financial Standard podcast Tune in each week as we discuss the latest developments in Australia's wealth management industry. |  |


The members of the FSC have always known the advisers responsible for the inappropriate advice/behaviour yet have not acted to stop it. The blame should lie at the feet of those responsible not with the overwhelming number of advisers that daily provide excellent advice to the people who need it.
LIF reforms as they currently stand will only increase the cost of advice and drive more people to platform (superannuation ) and direct insurance which we all know to be less comprehensive and or more expensive. These reforms which ASIC support will be the next big issue for ASIC in the insurance space as consumers face poor claims outcomes as they were forced into these products without knowing the differences in quality and price.
Fixing the problem that ASIC has identified is simple under the current rule, it just requires the three major players to do their job, ASIC (police) which they are now starting to do, licensees be responsible for their AR's actions (withdraw AR status on known offenders) and Insurers not dealing with the known offenders or encouraging some of these behaviours.
It's simple, effective and doesn't require more regulation.
1. Code of conduct Hmmmm, not one word in it about looking after the interests of clients!
2. Remuneration, thanks for HALVING our income and setting us on a path to only 20%, being a fifth our income (my husband and kids send their thanks).
3. LIF 'seismic reform' only seismically increases banks/insurers already record profits
4. LIF - Can you tell us one consumer benefit and prove it?
5. Democracy - did you give your members the opportunity to vote on whether they support the seismic industry changing legislation?
6. EGM - so many members in so short a time want to have their say on the LIF, can you ignore all of them?
7. There was no DIRECT correlation with upfronts with ALL advisers in ASIC 413
Please tell us one benefit for consumers in the LIF that you so ardently support.